Building Wealth by Example
Get a free consultation today.
We make it easy
Our way - the RealWay, is to be with you every step along the way. From initial consultation, to settlement and many years beyond, we wish to make your experience of property purchasing easy, unique, educational and exciting. We take care of all the paperwork and are always available to answer questions along your way!
You are unique!
Everyone is unique, same as financial situation and choice. Decision you make today will make huge difference to your future. That’s why we are here, helping you get ready for today and plan for tomorrow. We take time to listen to your needs, assess your financial ability, structure the right loans and help you to make decision that you will not regret in the years to come.
We care about our clients.
We value our clients’ trust, and strive to build long –lasting relationship with our clients.
We are paid by the respective lender, our service to you, is a complimentary service. We do not charge fees for credit or structure advice or to find you the suitable deal each and every time. Annual reviews of your loans are at no cost either.
Get a free consultation call today
At RealWay Finance, we dream your dream.
We provide mortgage broking services to property investors and home buyers. We help, advise and empower our clients along the journey of property investing, through our professional knowledge, hands-on experience and real passion.
RealWay, your way, our way.
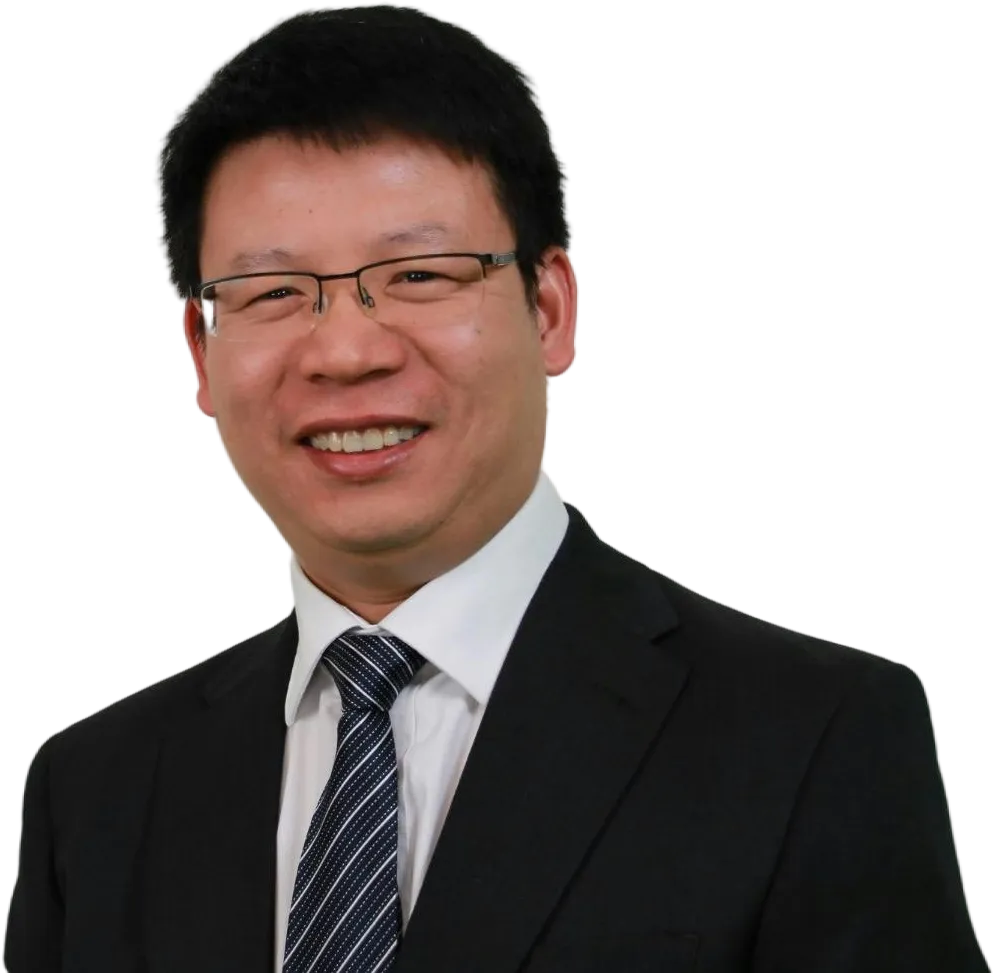
Junmin (Eric) Wu
Director, Mortgage Broker at RealWay Finance Pty Ltd

Junmin (Eric) WU is a credit representative (490993) of Mortgage Specialists Pty Ltd (Australian Credit Licence 387025)
MFAA Full Member Number 304158
Services
Property Investors
Assisting property investors reach their goals
At RealWay, we are investors ourselves so we understand the journey you're on.
We take the time to understand your goals, and your strategies to get there through property investing. We find the right loans and structure them correctly to suite your strategies.
Home Buyers
The best loans and rates for your needs
Every home owner is different. We make sure we understand your needs in a home loan for your unique situation. This could be fixed, variable, a mixture or just the loan with the lowest interest rate. We make sure we advise you on your options and what will be of greatest benefit to you now - and in the future.
Refinancing
Save on your current rate or access your equity
We do complimentary checks on your loan(s) to see if you can get a better loan product, access equity or should change banks to get a better deal.
BOOK A CALL NOW
What client say about us
latest news and insights
Here's what's going on in the world of finance and property.
Why holding out for lower prices could hurt first home buyers
In today’s easing market, it may be tempting to wait for property prices to fall further. But it’s a strategy that could see first home buyers left disappointed. We explain why.
There is no shortage of media headlines touting big falls in home prices.
But the reality may be less sensational.
While some property values at the luxury end of the market could be seeingprice falls of up to 10%, it’s a very different picture at themore affordable end of the market.
We look at what’s happening with home prices, and why holding out for prices to fall further could work against first homebuyers.
Good news for buyers: values have softened in most capital cities
The big picture is that home values nationally dropped 3.1%over the three months to September, taking annual price growth to just 2.7%, Cotality reports.
However, conditions vary between capital cities, and across market segments.
And here’s what first home buyers need to know.
Higher-value housing is recording larger price declinesthan affordable homes.
The affordable end of the market is proving resilient
As Cotality puts it, high-end homes are leading the downturn, whilelower-priced houses and unitsare proving more resilient.
As a guide, in the three months to August, property values across the top 25% of the Sydney market fell by 5.7%. By comparison, values in the most affordable 25% of the market,fell by just 2.1%.
In Melbourne, the most expensive segment of the market saw values fall 5.3%, while the cheapest quarter of the market saw prices drop by just 1.3%.
And it’s a similar pattern across almost every state capital, Cotality research shows.
Hobart and Darwin bucked the trend, with home values in the most affordable segment of their respective markets rising over the last quarter.
These findings matter for first home buyers.
That’s because most first-time buyers start out in the more affordable end of the market – and that’s exactly where home values are experiencing softer price falls, if any at all.
Why are affordable homes seeing lower price falls?
Several factors are helping to limit price falls across affordable neighbourhoods.
These include steady entry-level demand.
In the June quarter of 2026, for example,over 29,000 first homebuyers purchased a place of their own. That’s about the same number for the same quarter in 2025.
Demand for affordable homes is also being supported by a range of first home buyer initiatives such as the5% Deposit Scheme, theFirst Home Owner Grantand stamp duty savings initiatives.
It can also come down to numbers. There are simply fewer people who can afford to buy a luxury home.
What does this mean for first home buyers?
“Affordability” is the name of the game for plenty of today’s home buyers.
That’s becausethree rate hikesthis year havereduced the borrowing powerof many buyers.
Not surprisingly, that’s seen plenty of Australians hone in on affordable suburbs, which remain sought-after for their lower entry prices.
Across some cheaper suburbs, thenumber of online buyer searcheshas more than doubled compared to a year ago.
This doesn’t necessarily mean prices will rise in these neighbourhoods.
However, an increase in the number of buyers competing for a limited number of affordable homes may put upward pressure on prices – or limit the extent of any future price falls.
Talk to us today
Asaffordability pressures push demand toward cheaper markets, lower-priced suburbs may continue to be hot property among budget-conscious buyers.
This could see values in these areas hold their ground – or even buck the trend by starting to climb higher.
The bottom line is that if you’re a first home buyer, and you’re waiting for home prices to fall further, you could be disappointed.
Talk to us today to know if you’re home-loan ready right now.
Disclaimer: The content of this article is general in nature and is presented for informative purposes. It is not intended to constitute tax or financial advice, whether general or personal nor is it intended to imply any recommendation or opinion about a financial product. It does not take into consideration your personal situation and may not be relevant to your circumstances. Before taking any action, consider your own particular circumstances and seek professional advice. This content is protected by copyright laws and various other intellectual property laws. It is not to be modified, reproduced or republished without prior written consent.